

Insurance for Graphic Designers
Prepare for the unexpected with business insurance.
Up to $20 million Public Liability cover
Up to $10 million Professional Indemnity cover
4.7/5 Customer Rating

Compare Quotes
From multiple insurers

Save Time
Buy online in minutes

Save Money
Switch and save

Instant Cover
Delivered to your inbox
Compare Quotes
From multiple insurers
Save Time
Buy online in minutes
Save Money
Switch and save
Instant Cover
Delivered to your inbox
What is graphic designer insurance?
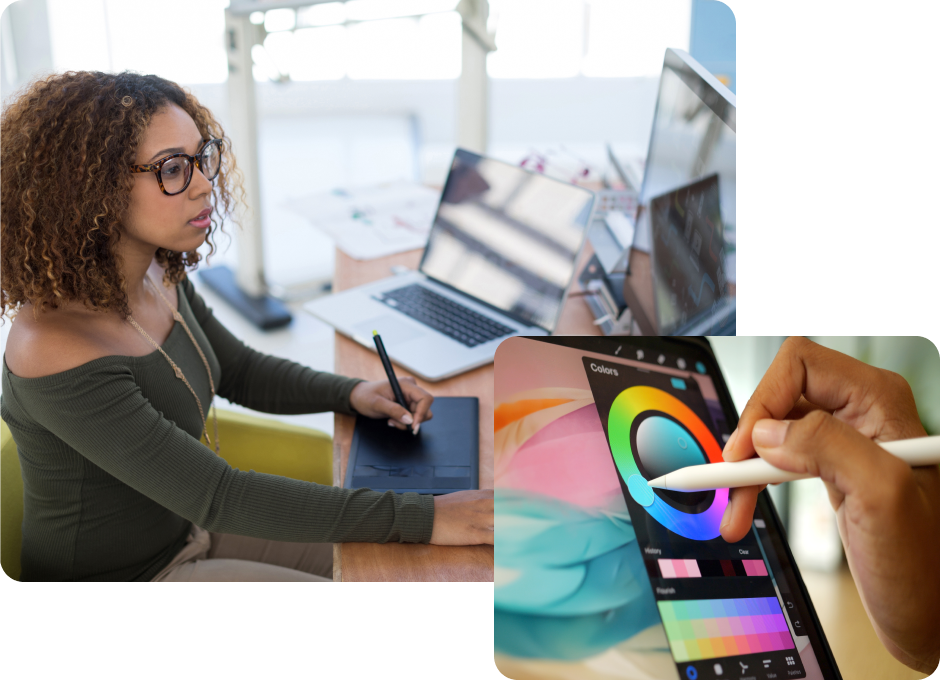
Graphic designers, design studios, and freelance creatives can customise their insurance to cover the unique mix of risks their business faces. From errors and omissions, intellectual property infringement, to equipment loss and cyber security risks. At BizCover we can help designers find the right insurance for their business needs.
Why do graphic and creative designers need insurance?
Working in the exciting and creative design industry means there is always new clients and projects to work on. The industry has so many different fields and branches of design work, that no two days are ever the same.
Design work requires accuracy and precision, a single mistake can prove costly. Business insurance can help designers with:

The cost of accusations of intellectual property infringement
Meeting requirements for leasing a design studio space
Legal fees associated with negligence or mistakes in design work
Meeting contractual requirements
Let’s cover your small business on the go
Start a quote to see how much you can save and buy online in minutes.
Save time & money by buying online in minutes.
What types of insurance do Graphic Designers need?
With BizCover, Graphic Designers can customise business insurance, select different cover options, and only pay for the cover they want.

Popular cover for Graphic Designers:


Graphic Designers could also consider:
Other Covers

Cyber Liability

Cyber Liability insurance
Covers your business from legal costs and expenses caused by cybercrime incidents such as:
- Data breaches
- Extortion
- Forensic investigation
- Business interruption
Business Insurance Package
Business Insurance Package
Choose cover options such as:
- Building cover
- Contents (Property) cover
- Tools & Portable Equipment cover
- Business Interruption cover
19000+ NZ
small business covered
How much does Graphic Designers’ cost?
Business insurance for Graphic Designers has an average expected cost of $78 per month with BizCover*.
The prices are real, get that new policy feel
How is the cost of insurance calculated?

Risks of the industry
Cover level amount
Annual turnover
Number of employees
Claims history
*Customer Average Monthly Payment Report is based on 1 July 2025 to 30 June 2026 and presented as a guide only. It may not reflect pricing for your particular business, as individual criteria will apply
Get cover that grows with your business
Select different cover amounts for each of your policies. Including Professional Indemnity up to $10 million, and Public Liability up to $20 million.
Unsure how much to choose? Think about:

Statutory Profession Requirements
Cover required by contracts
Number of employees being covered
Your contract value
Worst case scenario claim size
Underinsurance
We know it’s tempting to select a lower level of cover to reduce premiums, but this can leave businesses shocked and insufficiently covered when making a claim.
Ways underinsurance catches business owners out:
Inflation
With inflation, the cost of living and doing business increases. Remember to cover you, your tools and assets for the rising costs of replacing or covering them, not what you paid for them – you may be surprised at the difference.
Not covering the full cost of your risks
If you select cover levels for less than the value you may be found liable – left out of pocket when it comes to claims time. It’s important to review your risks and determine how much you will need to cover any claim that may come your way.
Public Liability
$85.06/mo*
Expected average cost small businesses to pay
Professional Indemnity
$15.94/mo*
Expected average cost small businesses to pay
Factors influencing cost
Your Industry
Required Coverage
Your Turnover
Number of Employees
Claims History
Click here to check industry wise average prices
*Customer Average Monthly Payment Report is based on 1 July 2023 to 30 June 2024 and presented as a guide only. It may not reflect pricing for your particular business, as individual criteria will apply.
Get cover that works with the risks of your business
You can select from 5 different levels of cover.
This is the most you will be paid out if you need to make a claim. Choosing different cover levels may impact the cost of your policy.
Unsure how much to choose? Think about:
Statutory professional requirements
Cover required by contracts
Number of employees being covered
Your contract value
Worst case scenario claim size
Underinsurance
We know it’s tempting to select a lower level of cover to reduce premiums, but this can leave businesses shocked and insufficiently covered when making a claim.
Ways underinsurance catches business owners out:
Inflation
With inflation, the cost of living and doing business increases. Remember to cover you, your tools and assets for the rising costs of replacing or covering them, not what you paid for them – you may be surprised at the difference.
Not covering the full cost of your risks
If you select cover levels for less than the value you may be found liable – left out of pocket when it comes to claims time. It’s important to review your risks and determine how much you will need to cover any claim that may come your way.
How it works – buying online
5 easy steps to get instant cover online today.
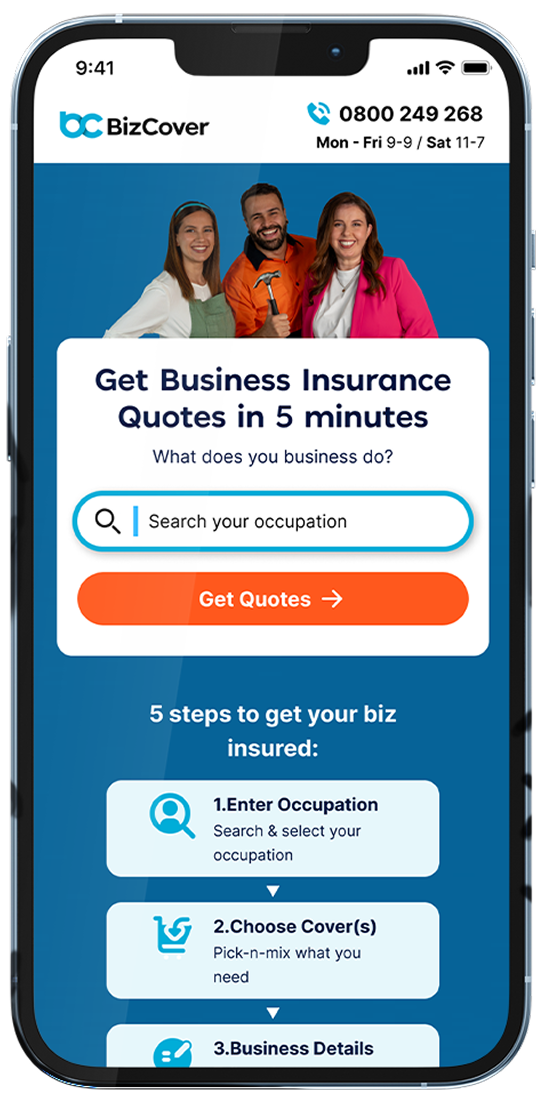

Select Profession

Pick Your Covers

Add Business Details

Compare Quotes

Get Covered Online

Search your
Occupation

Choose your
Cover(s)

Enter Business
Details

Compare
Quotes

Get Covered
Today
How it works – making a claim
We’ll assist you through the claims process & manage your claim directly with the insurer.
Let us know Fill out our claims form and provide info to support the claim
Receive extra support We will assist you with your claim
Claim results We will notify you of the claim outcome.
Let us know Fill out our claims form and provide info to spport the claim
Receive extra support We will assist you with your claim
Claims results We will notify you of the claim outcome
Our Insurers
We work with a selected group of trusted NZ insurers to offer you great cover.


The savings are real
See how much others have saved while purchasing policy through Bizcover
Chetan
An Accountant
from Auckland
Saved
$2000
on
Professional Indemnity insurance
Ivan
An Accountant
from Auckland
Saved
$200
on
Professional Indemnity insurance
Fran
An Accountant
from Christchurch
Saved
$1800
on
Professional Indemnity, Public Liability, Employers, and Statutory Liability insurance
Hector
An Accountant
from Auckland
Saved
$800
on
Professional Indemnity insurance
Margret
An Accountant
from Auckland
Saved
$1000
on
Professional Indemnity insurance
^ Savings made from February to July 2025. This information is provided as a guide only and may not reflect pricing for your particular business, as individual underwriting criteria will apply.
Frequently asked questions
There are no laws mandating business insurance for Graphic Designers, but they may be required to hold a certain type of business insurance in some circumstances, such as working on certain contracts or leasing commercial real-estate spaces.
It can, depending on the policy. Make sure you include web design in the services you tell us about when you get a quote, and check the policy wording to confirm what’s covered.
A claims-made policy is designed to provide cover when a claim is first made against your business during the policy period. This means claims first made against you after your policy ends generally aren’t covered, so it’s important to keep your cover in place. Let your insurer know as soon as you become aware of a claim.
Once you have purchased a policy with BizCover, your certificate of currency will be sent straight to your inbox. You can also login into your BizCover account to view and download a certificate of currency and your policy documents.
Hear from our customers
Efficient

Trusted Customer
Efficient and great price
Quoted and bought insurance online, very quick and a great price.
Definitely worth
Burnett B
BizCover is definitely worth their word. Quick easy understandable cover
Straight forward
Trusted Customer
It is very straight forward and easy to understand and you can choose whatever you need for your business.
Fast, friendly and efficient
Kylie T
The customer service agent was excellent. He explained to me clearly all the questions I had. Can’t be beat on price for the policy I needed and I was contacted within half an hour of my enquiry. Policy was confirmed on the phone. Excellent.


Real-life customer reviews verified by Feefo